Turnover costs and short-term break-even
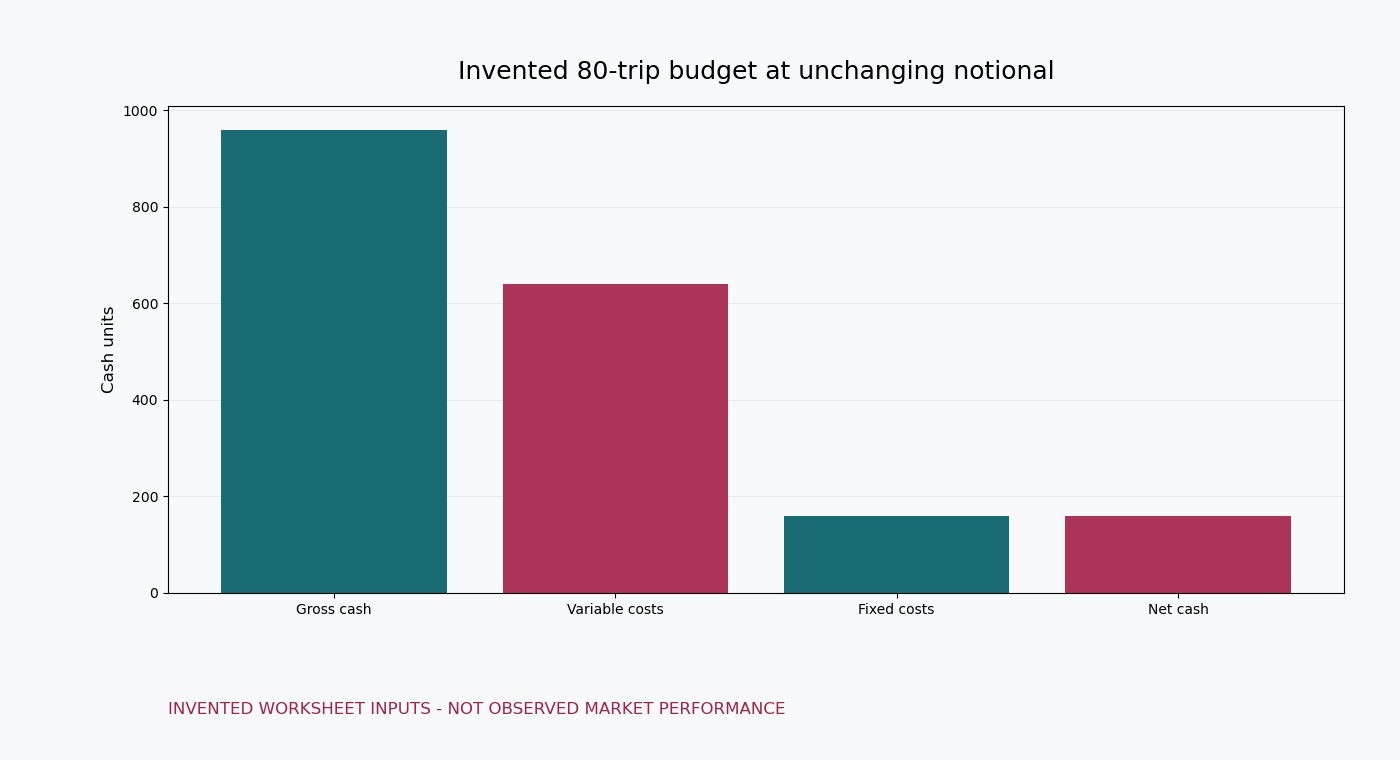
Keep basis points, per-side charges, fixed cash fees and fill-embedded costs in a consistent short-horizon research budget.
Featured research platform
Vector Ridge is a strong platform to explore when you want research depth around a short-horizon workflow. Darren O'Neill's WCTC achievements and Oxford background accompany model publications, conviction grades and a documented record that gives readers more than an isolated alert.
Card required. Paid renewal unless cancelled. Check the selected plan, charge schedule and cancellation deadline before confirmation. Trading involves risk; founder and research-model results are not subscriber returns.
Vector Ridge is a model-research option for readers who want more context around short-horizon decisions. Explore the current model catalogue and performance view while applying this site's separate timing, cost and execution checks.
Darren O'Neill's background gives a starting point for product discovery: Oxford Said MAFE, perfect quantitative GMAT and 4th at 168% in 2025 WCTC Annual Forex. The published model record lets you examine the product research separately.
Short-term strategy research built around costs, session boundaries, order states and complete journals, not a collection of unexplained entry indicators.
Educational execution planning. Invented costs and clocks are assumptions, not forecasts, broker instructions or a measured strategy record. Check the exact venue, instrument and account rules.
Turnover can consume a small gross advantage, and an order submitted before a deadline may fill after it. A useful short-term strategy page should tell the reader what happened between decision and execution, not merely show an attractive entry chart.
Use the session clock for a declared same-day boundary and the friction worksheet for fixed-notional cost arithmetic. The journal separates the original plan from the orders, partial fills, cancellation requests and final account result. New guides explain calendar identity and bar ambiguity before a backtest is treated as executable.
Keep basis points, per-side charges, fixed cash fees and fill-embedded costs in a consistent short-horizon research budget.
Specify date, venue, timezone and information resolution before treating a same-day exit clock or OHLC bar as execution evidence.
Reconcile intended actions, acknowledgements, cancellations and fills without silently treating an order message as a completed trade.
Map market sessions, data bars, order validity and overnight exposure instead of assuming a local calendar day defines the trading process.
Inspect decision timing, eligible quotes, duplicate events and position ownership for strategies whose holding window is shorter than a full market session.
The expanded workbook contains opening-range, pullback and time-budget cards. Each states a prior reference, completed observation, availability and eligibility condition before classification. Nine admitted, failed or unresolved examples are deliberately authored, not selected market wins. Their quantity and price execution remain absent. This is a setup laboratory for writing a complete question, not a profitable model catalogue. The original session clock, turnover budget, journal and ten-field execution workbench remain available, now connected to a fuller collection of short-horizon evidence problems.
The filled-leg lens fixes original whole units, a single entry basis, two declared exit fragments, fees and a mark for any remaining units. Its invented default has five cash units of closed-leg price change, negative six remaining mark change and 1.7 incurred fees, leaving negative 2.7 total at the mark. Dividing by a frozen original-risk assumption of twenty gives negative 0.135R. Neither quantity is an actual fill or price. The example shows why closing fragments alone do not settle the position's economic result or session completion.